


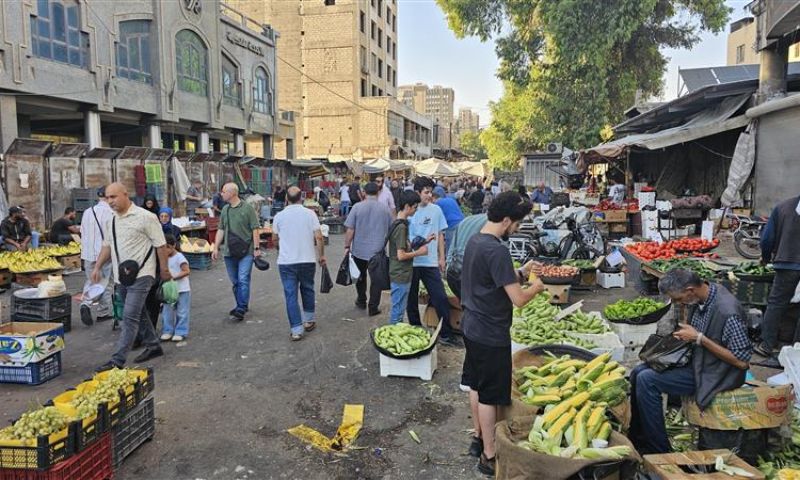
 Residents shop at the old wholesale market, September 16, 2026 (Enab Baladi/Ahmad Maslamani)
The Syrian pound weakened against the US dollar on the parallel market on Sunday, November 15, with the dollar’s selling rate exceeding 150 Syrian pounds and its buying rate reaching 149.50 pounds.
A Syrian economist told Enab Baladi that the decline was driven by the state budget deficit, which weakens confidence in the pound and increases demand for dollars.
The decline comes compared with levels at the beginning of November, when the dollar traded at 143 pounds for buying and 143.75 pounds for selling, representing a loss of approximately 4.3% in the pound’s value during the first half of the month.
According to prevailing market rates, the dollar’s buying rate rose from 143 pounds at the beginning of the month to 149.50 pounds, while its selling rate increased from 143.75 to 150.25 pounds, a rise of 6.5 pounds (approximately $0.04) in both rates.
Meanwhile, the Central Bank of Syria continued to maintain its official exchange rate at 121.50 new Syrian pounds for buying and 122.50 pounds for selling, unchanged from the levels set at the beginning of the month.
This reflects the continuing gap between official and parallel-market rates. The dollar’s selling rate on the parallel market is 27.75 pounds (approximately $0.18) above the official rate, while the difference in buying rates stands at 28 pounds (approximately $0.19).
The state budget deficit is one of the factors putting pressure on the Syrian pound against the dollar as the gap between government revenue and expenditure widens. The longer the deficit persists, the more markets question the government’s ability to cover its spending and secure resources, and whether it will resort to financing methods that could increase liquidity in the economy.
Syrian Finance Ministry data show that public revenue reached approximately $2.7 billion in the first half of 2026, compared with expenditure of $3.7 billion, leaving a deficit of nearly $1 billion.
Economist and banking expert Dr. Mahmoud Abdul Karim told Enab Baladi that the deficit undermines confidence in the pound but does not necessarily mean the government has injected additional local currency into the market.
According to Abdul Karim, the deficit’s monetary impact depends on how the state finances its spending, including whether it relies on short-term financing instruments or borrows directly from the Central Bank of Syria.
Finance Minister Mohammed Yisr Barnieh said at the end of August that the ministry was relying on short-term financing without borrowing from the central bank or injecting additional liquidity into the market.
On that basis, Abdul Karim believes there is insufficient evidence that the deficit has so far caused a substantial increase in the money supply. However, he noted that a persistent deficit and the way it is financed could influence the exchange rate even without a direct injection of money.
The budget deficit affects the pound through several channels, extending beyond the amount the state spends to include market participants’ expectations about future fiscal and monetary conditions.
Abdul Karim identified three main channels:
– How the deficit is financed: Financing state expenditure through instruments that do not directly inject money has a different impact from financing the deficit through the central bank and issuing more currency. Financing choices are therefore a key factor in determining the scale of pressure on the pound.
– Market confidence: Fears that the deficit will persist or widen may encourage residents and traders to hedge by buying dollars or gold, concerned that the pound’s purchasing power will decline. These expectations can increase demand for foreign currencies before any direct monetary impact of the deficit emerges.
– The state’s ability to increase revenue: The more difficulty the government has collecting sufficient revenue to cover expenditure, the greater its financing needs become. This raises questions about the sustainability of fiscal policy and its ability to limit monetary pressures.
In Abdul Karim’s assessment, the dollar’s current exchange rate does not appear excessive given existing economic pressures. Rather, it can be explained by declining confidence in the pound, concerns about the fiscal deficit and inflation expectations.
Abdul Karim linked the future direction of the exchange rate to the government’s ability to contain the deficit and secure stable financing, alongside the volume of foreign currency flowing into the country.
He outlined three possible scenarios:
– The dollar continues to rise gradually if the deficit persists and the government cannot increase revenue or improve market confidence in its ability to finance expenditure.
– The dollar declines gradually if public revenue improves, spending is brought under control and actual investments bring in foreign currency, strengthening the economy’s ability to meet its needs.
– The dollar rises more sharply if the deficit widens and the treasury is forced to finance it directly through the central bank, potentially increasing the money supply and intensifying pressure on the pound.
Central bank intervention through dollar sales could temporarily lower the dollar’s exchange rate. However, Abdul Karim believes lasting stability for the pound and a sustained decline in the dollar require actual foreign currency inflows, improved state resources and measures to address the imbalance between revenue and expenditure.
The pound’s ability to regain value therefore depends on more than intervention in the foreign exchange market. It is also tied to the government’s ability to reduce the budget deficit, secure financing for expenditure and attract real investment that brings foreign currency into the country, without resorting to options that increase monetary pressures.
Markets in Syria are facing mounting pressure as the Syrian pound has weakened against the dollar and other foreign currencies on the parallel market in recent days. On October 26, the dollar traded at 142.75 pounds for buying and 143.50 pounds for selling.
At the time, Enab Baladi tracked the pound’s exchange rate since the beginning of October. The currency had started the month relatively steady, with the dollar’s parallel-market rate at 137.65 pounds for buying and 138.40 pounds for selling.
During the early part of the month, the pound remained within a narrow stability range, benefiting from a temporary balance between supply and demand.
Signs of weakness subsequently began to emerge as the dollar’s exchange rate rose to between 141 and 141.5 pounds. The pound thus gradually lost approximately 2.2% of its value over three weeks.
The Syrian pound lost some of its value between the beginning of October and October 26, as the dollar’s black-market rate rose from approximately 138.4 pounds to more than 143 pounds, representing a decline of nearly 3.5%, with most of the losses concentrated in the final few days of that period.
Dr. Mokhles Nazer, an economist and banking expert and former first deputy governor of the Central Bank of Syria, proposed developing a locally adapted version of the Inflation Shock Momentum index, ISM-SY, to forecast price trends in Syria.
In a post on his personal LinkedIn page, Nazer said the recent decline in the pound’s exchange rate against foreign currencies presents Syria’s monetary authorities with a complex dilemma requiring more accurate early warning tools.
Nazer believes the national currency’s depreciation leaves the central bank facing the question of how to respond to two difficult possibilities:
– Whether the current rise in prices is merely a temporary wave that will subside on its own.
– Or whether it marks the beginning of sustained inflationary momentum that will change market participants’ expectations.
According to Nazer, the central bank’s decision on monetary intervention and its timing depends on this assessment.
The economist linked the pound’s decline on the parallel market to several simultaneous shocks:
– A fiscal shock, with government expenditure exceeding revenue by approximately $1 billion in the first half of 2026.
– An energy shock following fuel price increases in September.
– Declining confidence in the banking sector because of restrictions on withdrawals and transfers.
Nazer noted a clear gap in the central bank’s existing traditional analytical tools. They rely on annual inflation averages and historical price movements, without the ability to distinguish the direction of a shock or quickly use detailed consumer basket data. As a result, the central bank detects inflationary pressures late, after they have appeared in the headline index.
if you think the article contain wrong information or you have additional details Send Correction


 A
A
A


 More Economic Reports