
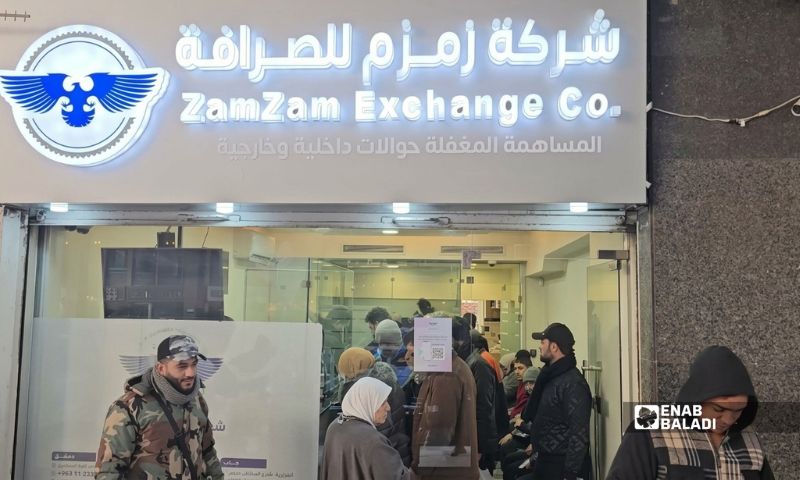

The Syrian pound has depreciated against the US dollar since Syria’s Ministry of Finance announced on August 31 that the state budget had recorded a deficit in the first half of 2026, with government spending exceeding revenues by approximately $1 billion.
On Wednesday, October 14, the dollar’s exchange rate on the parallel market stood at around 139 Syrian pounds for buying and 140 for selling, marking a slight improvement in the pound’s value of just one Syrian pound compared with the previous day. The currency remains under growing pressure amid rising fuel prices and a widening gap between official and parallel market exchange rates.
The latest depreciation has also raised questions about the ability of fiscal and monetary policies to ease pressure on the pound, as banks continue to impose withdrawal restrictions and economic activity faces difficulties in accessing financing and foreign currency.
While banking economist and academic Dr. Mahmoud Abdul Karim attributes the latest decline to rising fuel costs and their impact on price expectations, monetary and banking policy expert Mukhlis al-Nazer, former first deputy governor of the Central Bank of Syria, argues that the problem extends beyond the amount of Syrian currency in circulation to include:
- Confidence in the local currency.
- Difficulties accessing funds.
- Weak inflows of US dollars into the market.
Fuel Prices Push the Dollar Higher
The dollar rose on the parallel market from approximately 132 Syrian pounds in September to nearly 140 in October, while the Central Bank of Syria maintained its official exchange rate at 121.50 pounds for buying and 122.50 for selling.
This divergence widened the gap between the two rates to nearly 15%. According to Abdul Karim, this means that people selling dollars at the official rate receive less than they would on the parallel market, encouraging traders and other market participants to avoid official banking channels and limiting foreign currency inflows into those channels.
Speaking to Enab Baladi, Abdul Karim linked the beginning of the latest increase in the dollar’s value to decisions to raise fuel prices, particularly the September 13 pricing bulletin, which increased diesel prices by approximately 40% and gasoline prices by between 26% and 28%.
In his assessment, the primary effect of these decisions was not an increase in actual demand for dollars to import fuel. Rather, higher fuel prices translated into increased costs for production, transportation, agriculture, and the operation of generators and bakeries, all of which contribute to the prices of a wide range of goods and services.
According to Abdul Karim, the main ways in which fuel price increases affect the exchange rate can be summarized as follows:
- Higher production and transportation costs: Rising diesel and gasoline prices increase the cost of transporting goods and operating agricultural, industrial, and service facilities.
- Rising inflation expectations: Consumers and traders fear further increases in commodity prices, prompting some to purchase dollars or gold to protect their savings.
- Speculation: Some market participants may exploit expectations of a rising dollar to make profits, particularly at the beginning of periods of exchange rate volatility.
The market is also becoming increasingly sensitive to global oil prices because Syria relies on imports to meet part of its petroleum needs. As import costs rise, public finances and consumers face additional pressure, whether through higher spending on imports or the transmission of these costs to fuel and commodity prices.
Budget Deficit Undermines Confidence
Finance Ministry data showed that public revenues reached approximately $2.7 billion in the first half of 2026, compared with expenditures of $3.7 billion, resulting in a deficit of nearly $1 billion.
Abdul Karim believes the deficit puts pressure on confidence in the Syrian pound but does not necessarily mean the government has injected additional quantities of local currency into the market. The monetary impact of the deficit depends on how the government finances its spending, whether through short-term financing instruments or direct borrowing from the Central Bank.
Syrian Finance Minister Mohammed Yisr Barnieh stated in late August that the ministry relies on short-term financing without borrowing from the Central Bank or injecting additional cash liquidity into the market.
On that basis, Abdul Karim sees insufficient evidence that the deficit has so far led to a substantial increase in the money supply. However, he warns that the method used to finance it will remain an important factor in determining the direction of the exchange rate.
According to this assessment, the deficit’s impact on the pound depends on three main factors:
- Financing method: Using financing instruments that do not directly inject cash into the economy differs from financing spending by printing additional currency.
- Market confidence: Concerns about a continuing deficit may increase demand for dollars even before any direct monetary impact becomes apparent.
- Public revenues: The significant dependence of government revenues on the energy sector makes public finances more vulnerable to fluctuations in oil prices and fuel costs.
Abdul Karim estimates that the dollar’s current exchange rate does not appear excessive given existing economic pressures. Instead, he considers it consistent with the pound’s depreciation, rising fuel costs, and inflation expectations.
He outlines three possible scenarios for the exchange rate in the coming period:
- Baseline scenario: The dollar continues to rise gradually if fuel prices remain at current levels and pressures related to energy costs and inflation expectations persist.
- Positive scenario for the pound: The dollar gradually declines if oil prices fall, domestic fuel prices are reduced, and actual investment inflows provide additional foreign currency.
- Negative scenario: The dollar rises further if oil prices increase, new decisions raise fuel prices, and the Treasury is forced to seek direct financing from the Central Bank.
Central Bank intervention through dollar sales could temporarily lower the exchange rate, Abdul Karim said. However, he believes a sustained decline would require actual foreign currency inflows, increased oil production, or lower fuel prices.
Why Do Withdrawal Restrictions Fail to Lower the Dollar?
In a LinkedIn post on October 12, Dr. Mokhles al-Nazer argued that restricting bank withdrawals does not necessarily reduce demand for dollars and may instead increase it. He maintained that the decisive factor is not merely the amount of Syrian currency in circulation, but people’s confidence in the currency, their ability to use it, and their access to savings.
Al-Nazer explained that economic theory assumes a reduction in local currency liquidity could reduce demand for foreign currencies if other factors remain unchanged.
However, this assumption does not necessarily apply to Syria, where withdrawal restrictions coincide with concerns about the value of savings, difficulties in commercial activity, and a limited supply of foreign currency.
According to al-Nazer, citizens or traders who cannot freely withdraw their money may interpret these restrictions as evidence of a monetary problem. When they obtain part of their funds in Syrian pounds, they may rush to convert them into dollars or gold rather than retaining the pounds or depositing them in banks.
Al-Nazer identified four main sources of demand for dollars under current conditions:
- Loss of confidence in the pound and banks: Difficulties accessing savings encourage some citizens and traders to purchase dollars or gold as soon as they obtain liquidity.
- Imports outside official channels: Restrictions on transfers and banking procedures may push some traders to obtain dollars in cash to cover their requirements for goods and essential materials.
- Limited foreign currency supply: Restricted exports, weak tourism revenues, and hesitation among foreign investors reduce dollar inflows into the market.
- Declining formal economic activity: Burdens imposed on businesses may weaken production and investment, encouraging some holders of capital to speculate in currencies in search of quick profits.
According to al-Nazer, the problem is not limited to demand. The weak supply of dollars is also a fundamental factor behind the currency’s rising exchange rate. In a market with limited supply, even a modest increase in demand can move the exchange rate, despite a shortage of Syrian pound liquidity.
He also warned that increasing burdens on formal economic activities could weaken production and investment rather than stimulate capital circulation and expand employment opportunities.
Restoring Confidence Instead of Restricting Liquidity
Al-Nazer, the former deputy governor of the Central Bank, believes addressing pressure on the Syrian pound requires more than reducing the amount of money in circulation. Instead, the process should begin by restoring confidence in the banking system and improving the economy’s ability to generate foreign currency.
He proposed four main measures:
- Gradually easing withdrawal and transfer restrictions: Allowing citizens to access their money would reduce the incentive to convert savings into dollars or gold and keep them outside the banking system.
- Supporting production and exports: Reducing burdens on the industrial and agricultural sectors and encouraging activities that produce exportable goods and generate foreign currency revenues.
- Increasing monetary policy transparency: Narrowing the gap between exchange rates, simplifying procedures for traders, encouraging transactions through official channels, and publishing clear and consistent financial data.
- Improving the business and investment environment: Attracting genuine foreign investment that brings dollars into the economy, creates jobs, and stimulates production, rather than merely addressing the crisis’s temporary symptoms.
While the assessments presented by Abdul Karim and al-Nazer do not suggest that restricting liquidity alone is sufficient to stabilize the pound, both experts place confidence in the local currency, access to dollars, and the stimulation of productive economic activity at the center of efforts to address the crisis, rather than simply reducing the funds available to citizens and traders.